Belt and Road Markets Took 58.3 Percent of China Auto Export Value
Figures compiled by the China Association of Automobile Manufacturers from China Customs data and reported on 6 November 2026 put Chinese exports of automotive goods to Belt and Road partner countries at USD 135.77 billion for January to September 2026, up 32.6 percent year on year and equal to 58.3 percent of total automotive goods export value. Complete vehicle exports to those markets reached 5.598 million units, up 45.2 percent, including 2.042 million new energy vehicles, up 64.7 percent. The release covers vehicles and parts together, in US dollars, and does not separate used vehicles, so it is a demand indicator for these corridors rather than a used-car sales figure.
What Was Published
On 6 November 2026, several Chinese financial outlets reported the same set of figures compiled by the China Association of Automobile Manufacturers, known as CAAM, from China Customs data. They describe China's automotive exports to Belt and Road partner countries for the first nine months of 2026.
- Automotive goods exported to those markets: USD 135.77 billion, up 32.6 percent year on year.
- Share of total automotive goods export value: 58.3 percent.
- Complete vehicles exported to those markets: 5.598 million units, up 45.2 percent.
- New energy vehicles within that: 2.042 million units, up 64.7 percent.
Two arithmetic observations follow directly from those numbers, and both are ours rather than the association's. New energy vehicles account for roughly 36.5 percent of the complete vehicles shipped to Belt and Road markets, and markets outside that grouping account for the remaining 41.7 percent of automotive goods export value.
Scope: What These Numbers Actually Measure
The Chinese term behind "automotive goods" is 汽车商品, a customs trade category that combines complete vehicles with parts and components. It is broader than vehicle exports, and it is measured in US dollars of declared trade value, not in retail sales in the destination country.
That has three consequences for anyone quoting the figures.
First, the USD 135.77 billion cannot be divided by the 5.598 million vehicles to obtain an average vehicle price. The numerator includes parts, so any average computed that way is meaningless.
Second, the 58.3 percent share describes value, while the 5.598 million units describe volume. Comparing the two directly would mix different denominators.
Third, the period is January to September 2026 and the comparison base is the same months of 2025. Nothing in the release describes October.
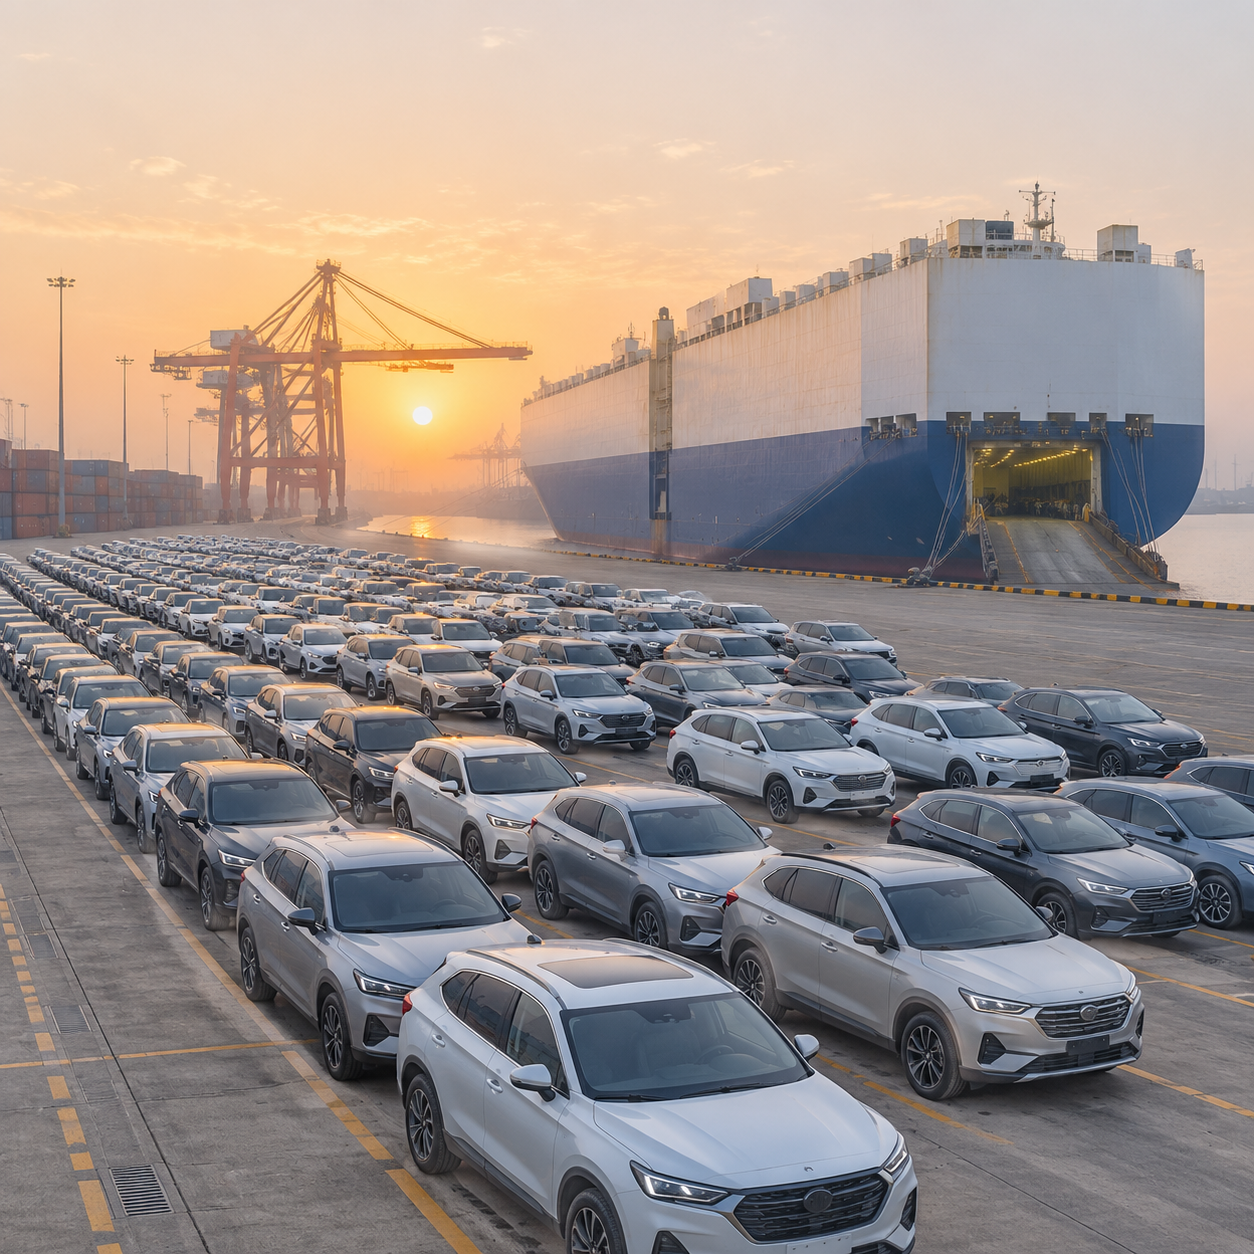
Volume Is Growing Faster Than Value
Complete vehicle volume to these markets grew 45.2 percent, while automotive goods value grew 32.6 percent. Those are different measures and should not be forced into one conclusion, but the gap is consistent with a trade mix shifting towards more affordable vehicles and towards markets where lower-priced models dominate.
For exporters, that is the commercially important reading: growth in these corridors is being driven by volume rather than by rising unit values. Competition on price is likely to stay intense, and margin has to come from sourcing discipline, logistics cost and after-sales capability rather than from assuming that customers will pay more next year.
New Energy Vehicles Are Growing Faster Still
At 64.7 percent, new energy vehicle growth to Belt and Road markets outpaces the 45.2 percent growth in total vehicle volume. New energy vehicles now represent about 36.5 percent of vehicles shipped to those countries, which means conventional petrol and diesel vehicles still make up the majority.
Both halves of that statement matter. The electrified share is rising fast enough that charging compatibility, battery documentation and high-voltage technician availability belong in any market plan. At the same time, roughly two thirds of the volume remains combustion-powered, so demand for petrol SUVs, pickups and sedans in these markets has not disappeared.
What This Means for Used Vehicle Exporters
This release does not identify used vehicles separately. China's used-car export programme moves vehicles through the same customs framework, and the published figures do not break them out, so these numbers must not be presented as used-car export volumes.
They are still useful as a demand signal. Markets that are absorbing more Chinese vehicles overall are the same markets where Chinese brands are building recognition, dealer networks and parts supply, and those three things determine how easily a used Chinese vehicle can be resold and maintained.
Practical implications for a used-vehicle business:
- Prioritise markets with established brand presence. A growing flow of new vehicles usually means better parts availability and more workshops able to service the same models later.
- Check the model-level picture before committing. A country-level growth figure says nothing about whether the specific variant you hold has local support.
- Plan for price competition. Volume-led growth brings more sellers into the same corridors, including new-car channels discounting aggressively.
- Treat electrified stock as a documentation exercise. Battery condition evidence, charging standard compatibility and local service capability decide whether a used electric vehicle is sellable, not the headline growth rate.
- Watch currency and payment terms. Values here are in US dollars; settlement currency and repatriation rules in each destination still determine realised margin.
What to Watch Next
- The October national export release, which will show whether the nine-month trend held into the fourth quarter.
- Country-level and model-level customs detail, which is where corridor-level averages stop being useful for purchasing decisions.
- Any change in import tariffs, homologation rules or used-vehicle age limits in the destination markets, which can redirect volume quickly.
- Full-year figures early next year, which will allow a like-for-like comparison with 2025.
Method and Caveats
The figures above are the CAAM compilation of China Customs data as reported on 6 November 2026 by Chinese financial media, including Jiemian and Zhitong Caijing. The outlet reports carry identical numbers, which indicates a common underlying release rather than independent measurement.
The grouping "Belt and Road partner countries" is a broad and evolving set of markets, not a fixed short list, and the release does not publish a country breakdown. Comparisons with other published export series should be made carefully: customs-based goods value, association wholesale data and passenger-car-only statistics are different measures and will not reconcile line by line.
No figure in this article is a used-vehicle export statistic, a destination-country registration figure or a retail sales figure. Percentages describing the new energy share and the non-Belt-and-Road value share are calculated from the published numbers and rounded to one decimal place.