H1 2026 Used Car Export Data: Volume Stabilizes, Quality Rises as Industry Matures
China exported ~305,000 used vehicles in H1 2026, a modest 8% YoY increase as the market shifts from explosive growth to consolidation. NEVs now account for 47% of exports. Average transaction price rose 22%. MOFCOM-licensed exporters dropped from ~3,000 to ~2,100, signaling industry-wide quality improvements.
H1 2026: A Watershed Moment for China's Used Car Export Industry
The first half of 2026 marked a pivotal shift in China's used car export sector. While growth continued, it was qualitatively different from the breakneck expansion of previous years. According to data released by the China Automobile Dealers Association (CADA) and General Administration of Customs, total used car exports reached approximately 305,000 units in H1 2026, representing an 8% year-over-year increase.
The moderate growth rate — down from 35% in H1 2025 and 80% in H1 2024 — signals that the industry is entering a consolidation and maturation phase, driven largely by the November 2025 MOFCOM policy that effectively banned zero-kilometer vehicle exports.
Key Data Points
Export Volume by Month (H1 2026)
| Month | Volume | MoM Change | YoY Change |
|---|---|---|---|
| January | 52,000 | -15% | +5% |
| February | 38,000 | -27% | +2% |
| March | 55,000 | +45% | +10% |
| April | 53,000 | -4% | +8% |
| May | 56,000 | +6% | +12% |
| June | 51,000 | -9% | +7% |
| Total | 305,000 | — | +8% |
Fuel Type Breakdown
- Pure Electric (BEV): 28% (85,400 units) — up from 19% in H1 2025
- Plug-in Hybrid (PHEV/EREV): 19% (58,000 units) — up from 13%
- ICE (Gasoline): 42% (128,100 units) — down from 55%
- ICE (Diesel): 11% (33,500 units) — stable
- Total NEV share: 47% (vs 32% in H1 2025)
Top 10 Destination Markets
| Rank | Country | H1 2026 Volume | Share | YoY Growth |
|---|---|---|---|---|
| 1 | Russia | 68,000 | 22.3% | +15% |
| 2 | Nigeria | 42,000 | 13.8% | +22% |
| 3 | UAE | 28,500 | 9.3% | +45% |
| 4 | Mexico | 24,000 | 7.9% | +85% |
| 5 | Kazakhstan | 19,000 | 6.2% | +40% |
| 6 | Uzbekistan | 16,500 | 5.4% | +120% |
| 7 | Kenya | 12,000 | 3.9% | +18% |
| 8 | Brazil | 10,500 | 3.4% | +200% |
| 9 | Ethiopia | 9,000 | 3.0% | +95% |
| 10 | Saudi Arabia | 8,000 | 2.6% | +60% |
Pricing Trends
- Average transaction price (CIF): $12,800 — up 22% from $10,500 in H1 2025
- NEV average price: $16,200 — up 28%
- ICE average price: $9,500 — up 12%
- Price increase drivers: Shift toward higher-quality vehicles, rising NEV share, removal of sub-$5K zero-kilometer units from the market
Exporter Consolidation
- MOFCOM-licensed active exporters: ~2,100 (down from ~3,000 in December 2025)
- Top 50 exporters now control 42% of total volume (up from 30%)
- Average revenue per exporter: $1.86 million (up from $1.02 million)
- Estimated 900 companies exited the market in H1 2026
Regional Highlights
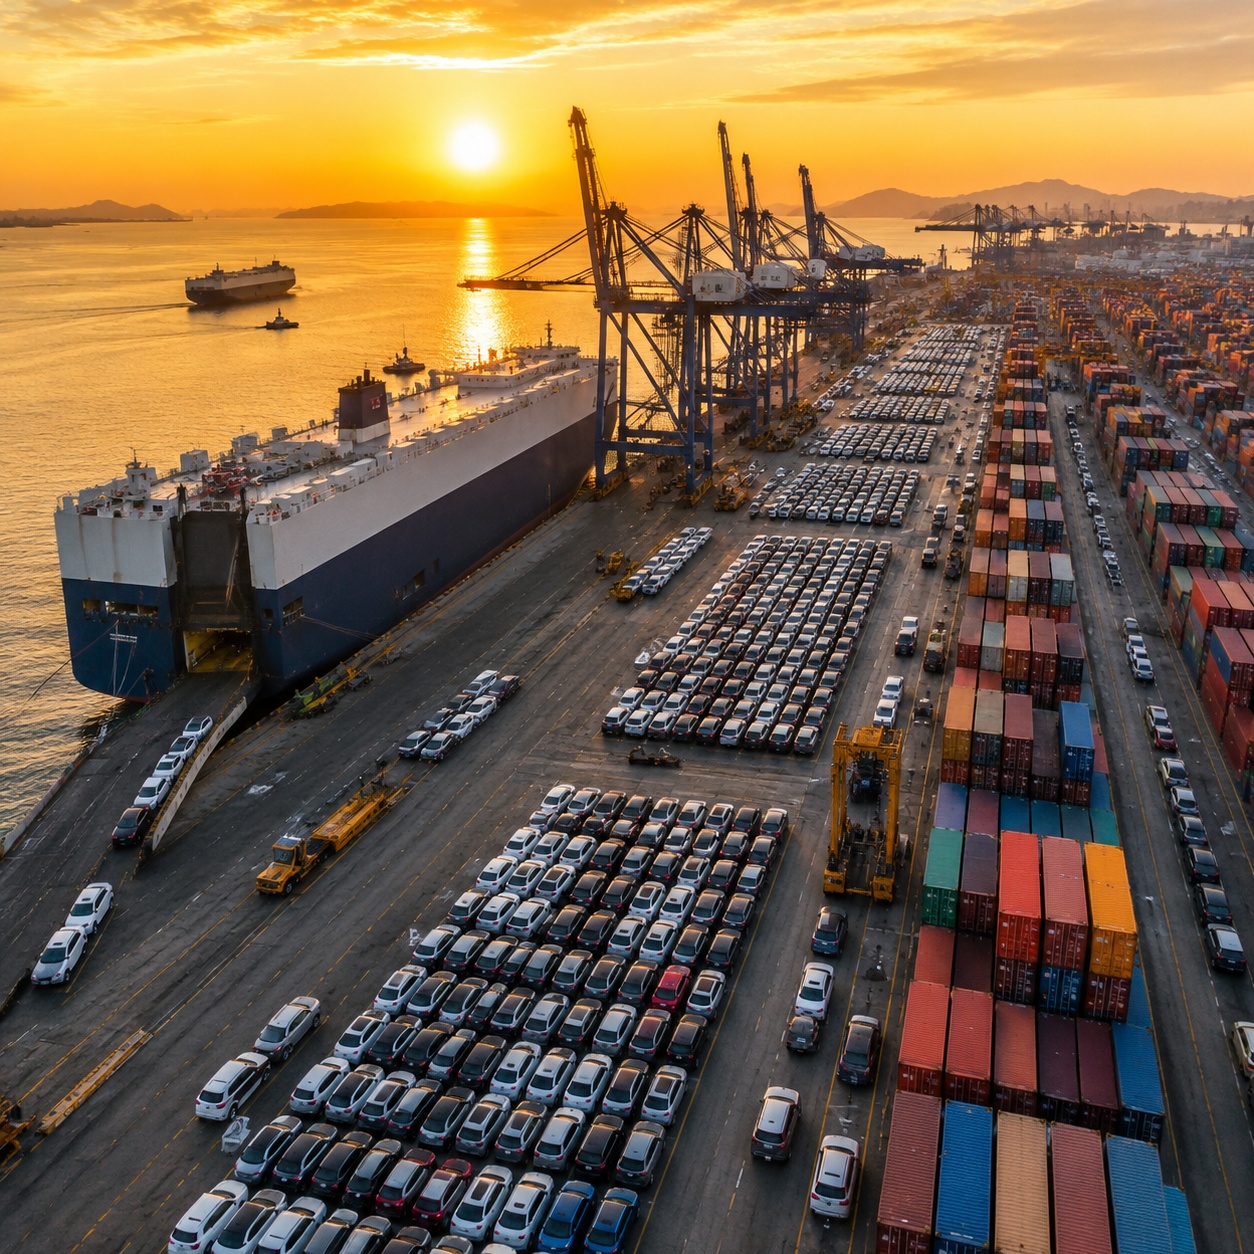
Russia: Still #1, But Shifting
Russia remains the dominant destination, absorbing 22.3% of all exports. However, the market is maturing rapidly:
- Chinese brands now command 38% of Russia's used car imports
- Demand shifting from budget sedans to mid-range SUVs and NEVs
- Manzhouli border crossing processed 2,800+ units/day at peak in May
- EV demand growing in Moscow and St. Petersburg driven by lower operating costs
Africa: Nigeria Leads, Ethiopia Surges
Nigeria solidified its position as Africa's largest importer of Chinese used cars. The Lagos port complex now handles an average of 7,000 Chinese vehicles monthly. Ethiopia emerged as the dark horse — its 95% YoY growth reflects aggressive government policies favoring NEV adoption with only 15% import tariff.
Middle East: UAE as the Regional Hub
The UAE's role as a re-export hub has strengthened dramatically. Approximately 65% of Chinese used cars entering Dubai's auto free zones are re-exported to other Gulf states, East Africa, and CIS countries. Dubai now rivals Mombasa as the primary transit point for vehicles destined for East Africa.
Latin America: Mexico and Brazil Break Out
Mexico has become China's fourth-largest used car export destination, driven by competitive pricing and improving Pacific shipping routes. Brazil posted 200% growth — albeit from a low base — as new tariff reductions on hybrid vehicles opened the market.
Policy Impact: The Zero-Kilometer Ban's Ripple Effects
The January 2026 implementation of the 180-day rule has reshaped the industry:
- Genuine used car share: Estimated at 75% of exports, up from 40% in 2025
- Average vehicle age: 2.8 years (up from 0.8 years in H1 2025)
- Average mileage: 42,000 km (up from 12,000 km in H1 2025)
- After-sales complaints: Down 35% as vehicle quality improved
H2 2026 Outlook
- Full-year forecast: 620,000–660,000 units (up 5–12% from 2025)
- NEV share expected to reach 50% by Q4 2026
- Further exporter consolidation: Estimated 1,500–1,800 active exporters by year-end
- Key risks: Red Sea shipping disruptions, currency volatility in key African markets, potential additional regulatory tightening
Bottom Line: 2026 is shaping up as the year China's used car export industry transitions from "grow at all costs" to "grow sustainably." Lower volume growth, higher quality vehicles, and professionalized exporters are the new normal.